Fiona Hall (packing her bags) - profile
 Mark Smith : 8 November 2019, 12:47:21 pm AEDT
About Fiona Hall director of Caernarvon Cherry Pty Ltd of Canobolas Rd, Orange NSW 2800.
96 min read
[2022] NSWSC 382
published 29 August 2022
Decision extracted and sourced from: https://www.caselaw.nsw.gov.au/decision/17ff234b71f1540bb837f52a#
Medium Neutral Citation:
In the matter of Caernarvon Canobolas Pty Ltd (In Liq) [2022] NSWSC 382
Hearing dates:20 – 23 July and 10 – 11 August 2021
Decision date:05 April 2022
Jurisdiction:Equity
Before:Ward CJ in EqDecision:
1. The appeal be allowed.
2. The liquidator’s determination to admit the proof of debt dated 15 November 2019 submitted by the second and third respondent be set aside and the proof of debt be rejected.
3. The second and third respondents pay the costs of:
(a) the applicant and the first respondent of and incidental to the amended interlocutory process in this proceeding; and
(b) the applicant and the first respondent (including liquidation costs, expenses and liquidators’ remuneration) of and incidental to the submission, consideration and determination by the liquidators of the proof of debt dated 15 November 2019 submitted by the second and third respondents.Catchwords:
CORPORATIONS – Winding up – Proceedings against company – Where debt disputed – whether parties reached agreement that costs of renovations would be recorded as a loan against the company
EVIDENCE – Documentary evidence – Business records – whether records were contemporaneous or issued retrospectively
ESTOPPEL – Promissory estoppel – Existing or expected legal relationship – whether the Company accepted or acquiesced to a benefit to the detriment of the second and third respondents
EQUITY – Equitable remedies – RestitutionLegislation Cited:
Corporations Act 2001 (Cth), ss 286, 477(2B), Schedule 2
Evidence Act 1995 (NSW), ss 48, 57(1), 58(1), 69
Supreme Court (Corporations) Rules 1999 (NSW), r 14.1(5)
Trustee Act 1925 (NSW), s 81Cases Cited:
Angas Law Services Pty Ltd (in liq) v Carabelas (2005) 226 CLR 507; [2005] HCA 23
Australia and New Zealand Banking Group Ltd v Westpac Banking Corporation (1988) 164 CLR 662; [1988] HCA 17
Australian Competition and Consumer Commission v Air New Zealand Ltd (No 1) (2012) 207 FCR 448; [2012] FCA 1355
Brick & Pipe Industries Ltd v Occidental Life Nominees Pty Ltd (1992) 6 ACSR 464; [1992] 2 VR 279
Briginshaw v Briginshaw (1938) 60 CLR 336; [1938] HCA 34
Broadway Plaza Investments Pty Ltd v Broadway Plaza Pty Ltd [2020] NSWSC 1778
Brodyn Pty Ltd v Dasein Constructions Pty Ltd [2004] NSWSC 1230
Capital Securities XV Pty Ltd (formerly known as Prime Capital Securities Pty Ltd) v Calleja [2018] NSWCA 26
Capocchiano v Young [2013] NSWSC 879
Commercial Union Assurance Company of Australia Ltd v Ferrcom Pty Ltd (1991) 22 NSWLR 389
Commonwealth v Verwayen (1990) 170 CLR 394; [1990] HCA 39
Damberg v Damberg (2001) 52 NSWLR 492; [2001] NSWCA 87
David Securities Pty Ltd v Commonwealth Bank of Australia (1992) 175 CLR 353; [1992] HCA 48
DHJPM Pty Ltd v Blackthorn Resources Ltd (2011) 83 NSWLR 728; [2011] NSWCA 348
Doueihi v Construction Technologies Australia Pty Ltd (2016) 92 NSWLR 247; [2016] NSWCA 105
Effem Foods Pty Ltd v Lake Cumberline Pty Ltd (1999) 161 ALR 599; [1999] HCA 15
El-Saafin v Franek (No 3) (2019) 143 ACSR 452; [2019] VSC 155
Falcke v Scottish Imperial Insurance Co (1886) 34 Ch D 234
Farah Constructions Pty Ltd v Say-Dee Pty Ltd (2007) 230 CLR 89; [2007] HCA 22
Federal Commissioner of Taxation v Cassaniti (2018) 266 FCR 385; [2018] FCAFC 212
Fitzgerald v F J Leonhardt Pty Ltd (1997) 189 CLR 215; [1997] HCA 17
Gregg v The Queen (2020) 355 FLR 348; [2020] NSWCCA 245
Grundt v Great Boulder Pty Gold Mines Ltd (1937) 59 CLR 641; [1937] HCA 58
Herdegen v Commissioner of Taxation (Cth) (1988) 84 ALR 271; [1988] FCA 699
Hill v Esplanade Wollongong Pty Limited (subject to a deed of company arrangement) [2018] NSWSC 478
Hutchinson v Sydney (1854) 10 Ex 438
In re Bailey, Hay & Co Ltd [1971] 1 WLR 1357
In re Express Engineering Works Ltd [1920] 1 Ch 466
In re Oxted Motor Co Ltd [1921] 3 KB 32
In the matter of Azmac Pty Ltd (In Liq) (2020) 146 ACSR 113; [2020] NSWSC 204
In the matter of Hillsea Pty Limited [2019] NSWSC 1152
Johnston v McGrath (2008) 67 ACSR 169; [2008] NSWSC 639
Jorden v Money (1854) 5 HL 185
Legione v Hateley (1983) 152 CLR 406; [1983] HCA 11
Lumbers v W Cook Builders Pty Ltd (in liq) (2008) 232 CLR 635; [2008] HCA 27
MYT Engineering Pty Ltd v Mulcon Pty Ltd (1999) 195 CLR 636; [1999] HCA 24
Parker & Cooper Ltd v Reading [1926] Ch 975
Pavey & Mathews Pty Ltd v Paul (1987) 162 CLR 221; [1987] HCA 5
Re ACN 096 281 542 Ltd (in liq) [2018] VSC 425
Re Duomatic Ltd [1969] 2 Ch 365
Re St Gregory’s Armenian School Inc (2015) 109 ACSR 27; [2015] NSWSC 1465
Rickard Constructions Pty Ltd v Rickard Hails Moretti Pty Ltd [2004] NSWSC 984
Rosseau Pty Ltd (in liq) v Jay-O-Bees Pty Ltd (in liq) (2004) 50 ACSR 565; [2004] NSWSC 818
Ryan v Dries [2002] NSWCA 3; (2002) 10 BPR 19,497
Spencer v The Commonwealth (1907) 5 CLR 418; (1907) 14 ALR 253
Sutherland (in his capacity as liquidator of Sydney Appliances Pty Ltd (in liq)) v Robert Bosch (Australia) Pty Ltd (2000) 33 ACSR 680; [2000] NSWSC 32
Tanning Research Laboratories Inc v O’Brien (1990) 169 CLR 332; [1990] HCA 8
Waltons Stores (Interstate) Ltd v Maher (1988) 164 CLR 387; [1988] HCA 7
Watson v Foxman (1995) 49 NSWLR 315
Westpac Banking Corp v Totterdell (1998) 20 WAR 150; (1998) 29 ACSR 448
Winterton Constructions Pty Ltd v Hambros Australia Ltd (1991) 101 ALR 363Texts Cited:
P L Davies, Gower and Davies’ Principles of Modern Company Law (7th ed, Sweet & Maxwell, 2003)Category:Principal judgmentParties:Timothy Hall (Plaintiff)
Bonny Glen Fruits Pty Ltd (First Defendant)
Bernard Hall (Second Defendant)
Bonny Glen Trading Pty Ltd (Third Defendant)
Caernarvon Canobolas Pty Ltd (Fourth Defendant)
Melrose Park Nashdale Pty Ltd (Fifth Defendant)
Frederick Charles Hall (Sixth Defendant)
Pamela Therese Hall (Seventh Defendant)Representation:Counsel:
D Smallbone with A Smyth (Applicant)
A Spencer (2nd and 3rd Respondents)
Solicitors:
MC Lawyers & Advisers (Applicant)
Matthews Folbigg Pty Ltd (2nd and 3rd Respondents)
File Number(s):2018/340546
Publication restriction:Nil
[Bernard] said: Fiona and I want to renovate the Homestead to fix some issues and make the house bigger for our kids. We have the money, and can use our own, but we are worried about what will happen if the Company ever sells or transfers the house. We want to make sure that we can get that money back if the Homestead is ever sold or transferred.
Tim said: Before you think about renovating, why don’t you look at subdividing the lot like I did at Melrose. If that doesn’t work then you can do the renovations.
[Bernard] said: Okay, Fiona and I will look into that and let you know how it goes.
Bernard said: We need to do some work to the Homestead because the old electricity is dangerous and we now have 2 young children and a Toddler. We want to renovate but it’s going to cost a lot because it’s an old house and like opening a can of worms, so our money needs to be recognised. We need bathrooms, a new laundry, electricity, new bedrooms, proper heating and such.
Tim said: Why don’t you go and look at other ways first like look at buying Armstrong’s [next door neighbour’s at Melrose] place or buying another house somewhere.
Pam said: Or why don’t you see if you can move the title and get 6 acres like Tim did? You’ve got these little kids and need something sorted as we just had a cold winter and the place is freezing. Something needs to be sorted.
Bernard said: Okay, we’ll look at other options.
- House @ Caernarvon
B&F expressed wanting to renovate house but for $ sunk into place to be recognised.
Tim suggest to look @ other options.
[Bernard] said: We spoke to a town planner and they won’t let us subdivide the lot. We still want to update the Homestead and extend it, so we want to go ahead with the renovations. How do we go about that?
They said: Where will you get the money from?
[Bernard] said: We can pay for the renovations ourselves or through Caernarvon Cherry, but we want all the money we put into the Homestead to be recognised if the place is ever sold or transferred to someone else.
Des said: You should also get a valuation before you do the renovations, and then another valuation after so you can see how much the Homestead is improved. It could be important if you need to pay some tax on it in the future.
[Bernard] said: Okay, we can do that. But more importantly we want to get our money back that we put in, so we want the money we spend on the renovations to be accounted for by the Company somehow.
Des said: Okay. Keep your receipts so that we can see how much you spend on the renovations and we can put that in the records of the Company as a debt owed to you and Fiona. Then the Company can easily pay you back if the Homestead ever sells. We can also make sure that you get paid interest, for example at an interest rate equivalent to the change in the Consumer Price Index until you are repaid.
[Bernard] said: That sounds like it does everything we want, let’s do that.
Des said: Does everyone agree to doing it that way?
Tim said: Yeah, I’m okay with that.
Bernard said: We’ve been told we can’t do a subdivision so we’re back to the drawing board and want to renovate 474 Canobolas.
Armstrong’s place want too much money and we want to stay on the property and don’t want to be living at Melrose and working at Caernarvon. Either way, it isn’t an option to build another house on Caernarvon because we’d have the same issues with wanting the money to be recognised because it would be Company land. So, we think we may as well renovate the Homestead.
Tim said: Okay.
Bernard said: We aren’t asking for money, just asking if we can spend own money on the place because we would be doing large scale renovations. How can we have our money recognised?
Des said: Keep all your receipts so that we can see how much you spend on the renovations and I’ll put that on the books of the Company. Each year we can add the CPI to the amount you’ve spent and it’ll be on the books as a loan. But if you do overcapitalise [sic]
Bernard said: Okay let’s do that. That’s fine, we will be responsible if we overcapitalise.
Des said: Get a valuation before you do the renovations, and then another valuation after that so that you don’t overcapitalise.
We said: Okay, if we do then that’s our money and we will be responsible for that.
Bernard spoke of Renovations required at Caernarvon house. Des advised to keep records of amounts spent so that amounts will be recorded & owed to B & F & increased in CPI’s.
Tim said: Perhaps one way if you were going to do any renovations to the house at Canobolas was to get a valuation of the house before and after the renovations. This way would work out what increase in the value was gained by such renovations rather than what you had spent.
[Des] said: Another way to record down what items you spent and from those items be approved by Tim and Bernard and recorded in the company financial records as a loan to you both (being the company financial records as a loan to you both (being Bernard and Fiona). Those costs could be adjusted by CPI and an adjustment made for each year of the increase in value as you could over capitalise the property and such costs not recovered in valuation method [sic]
Hi Fi
As discussed, I understand that personal funds you and Bern/Caernarvon Cherry Pty Ltd have available will be used to pay for the house renovations, and there will be an adjustment done to square things up with Tim based on the pre- and post- valuer of the house as it is owned by one of the Company’s that is 50% owned by Tim.
…
The other point that may be worth checking with Des is that the way you will be paying for the house renovations will be the most tax effective for the Company and yourselves individually. I suggest checking with Des to confirm that there are no other strategies he would suggest to assist with tax minimisation now and in the future.
It is my understanding at our meeting in Orange that Tim suggested pre and post valuation.
I suggested what ever [sic] you spent plus CPI would be adjusted and to resolve the issue I suggested the higher of the two.
The reason I explained you could over capitalise the property and such costs not recovered in the valuation.
With the current update to end of April figures you are sending I can work out the overall tax planning.
To assist please also provide estimate of renovations costs and timetable and what type of renovations.
hi des
I have just emailed you the backup of MYOB for April 30. We have done as suggested and had the house (and house only) valued before any renovations commence. I will pass this on once received.
The renovations will commence next week however I don’t envisage a lot of money being spent before the end of the financial year. There have been costs to council, draftsman, engineering, design etc so far, however my prediction that another 70k would be spent before end of fy at the most.
The total renovation is going to be an estimated [sic] at $400-450k, will give you some more details when the fixed quote comes in from the builder tomorrow.
(a) Variation and Instruction sheet number 5 dated 5 August 2014 for $18,441.72 for additional quotation for remove entire roof/blanket.
(b) Variation and Instruction sheet number 7 dated 5 August 2014 for $1,496.00 for building/waterproofing and tiling 2 wall niches for each bathroom.
(c) Variation and Instruction sheet number 8 dated 5 August 2014 for $352.00 for installation of in wall cistern to ensuite.
(d) Variation and Instruction sheet number 10 dated 5 December 2014 for $8,129.44 for extra cost on tile to wet areas.
(e) Variation and Instruction sheet number 11 dated 5 December 2014 for $1,067.00 for strip drain to wet areas as Reece prime cost amount has been taken off contract.
(f) Variation and Instruction sheet number 12 dated 5 December 2014 for $94.60.
(g) Variation and Instruction sheet number 15 for $7,449.20 for carpet cost not quoted in building works originally.
Caernarvon House
- Valuations of the house have been done before renovation and after. Des to contact the valuers to get true valuations. The difference between the valuations to be recorded as the expense was incurred by B&F hall personally
4.1 Caernarvon house improvements – Des was getting clarification from the valuers – Des forgot to do this – Des will follow this up to have a resolution by next meeting.
5. Residential properties on ‘Melrose’ and ‘Caernarvon’
- TH & BH agreed that there have been improvements to the residential properties on these 2 properties over time and that there may have been costs incurred by TH & BH on each of these respective properties from their own funds, and that such contribution needs to be taken into account when calculating the net asset ownership by TH & BH as part of the asset separation.
- The residential property on ‘Melrose’ is the residence of TH, and on ‘Caernarvon’ is the residence of BH
- Agreed that MT will obtain financial reports for the entities owning these properties from DL (and associated entities) to review the amounts reported in these financial reports/ balance sheet, and provide a summary to TH & BH of this financial information for further discussion as to the next steps to take to agree on the contribution made respectively by TH & BH to these properties.
We are instructed that Tim was aware that our client’s [sic] would be undertaking this work and that any amounts spent by Fiona and Bernard on the renovations, would be recorded as an amount owed to them in the books and records of the company, however, this did not occur.
… if Bernard and Fiona agreed to fund the repair and renovation of the Homestead and arrange for the said work to be carried out and 474 Canobolas was ever sold, the Company would repay the amounts so funded together with interest at a rate equivalent to the change in the Consumer Price Index over the period of the advance.
Q. Can you remember anything else that Des said at this meeting?
A. The only thing I can remember was that he did give us a few options, one was to get a valuation before and after. And the other one was to keep the receipts and he’d basically he’d put it into financials to, like, and then we’d be ‑ if down the track anything gets, you know, sold or whatever that ‑ or split, that we would be reimbursed at some point, or if not reimbursed like, you know, what's the word, like they’d be an equalisation, I suppose, something like the words to that affect [sic], and we could be repaid the equivalent of CPI, to the CPI. Words to that affect [sic], and I’m not 100%, you know, but I know there was a couple of things bandied around and one was definitely to get a valuation done before and after. And then to make sure we keep the receipts and we could be ‑ we would be reimbursed on the event that we ever sold or whatever, and we could be – he’d take, he’d take the CPI into account. That’s about all I can really tell you about that.
Q. These were options for you to consider and talk about amongst yourselves and decide on, is that it, if you wanted to?
A. Correct.
Q. You didn’t ever come to a definite decision about any of them, did you?
A. Well, we were waiting for ‑ no, you’re right, no
Q. The first advice from Des Lee wasn't the end of the matter because, at a later meeting, Bernard said, “We’ll be responsible if we over capitalise”, is that the sequence?
A. Des and Tim requested that we got some valuations done before the renovations and after the renovations.
Q. That told you, didn’t it, that you did not have agreement to recoup whatever you’d spent, is that right?
A. Well, it was our money going into the renovation, yes.
Q. You had no understanding that you would be entitled to recoup every dollar that you spent, is that right?
A. We were asking for just what we put into the place to be recognised, we weren’t asking for reimbursement.
Q. You accept, don’t you, that there was no promise by the company to pay you whatever you spent on these renovations?
A. And we weren’t expecting it at the time, we didn't expect that we'd be going through this process. We were happy to put our own money in to a very old house, with three little kids, to make it comfortable for us.
Q. It’s true, isn’t it, that this was all so long ago that you can't remember the precise order of the events of these discussions about the renovations and how the expenses might be recognised?
A. Well, we’d worked the time – I’d worked the timeline out plus the discussions that were had, I was very ‑ making sure that before we moved a brick that we were going to be recognised for our personal money, a lot of my parents’ money went into it as well.
None of the terms, “benefit”, “acceptance” or “expense”, can usefully be defined or applied without deciding whether attention is to be confined to the party who is identified as conferring the benefit and the recipient of that benefit, or account must be taken of the legal relationships that exist between one or other of those two parties and some third party or parties in relation to the events and transactions said to constitute conferring a “benefit”, its "acceptance", or the incurrence of expense.
… The general principle is, beyond all question, that work and labour done or money expended by one man to preserve or benefit the property of another do not according to English law create any lien upon the property saved or benefited, nor, even if standing alone, create any obligation to repay the expenditure. Liabilities are not to be forced upon people behind their backs any more than you can confer a benefit upon a man against his will.
**********
07 April 2022 - Amendment to representation on coversheet
DISCLAIMER - Every effort has been made to comply with suppression orders or statutory provisions prohibiting publication that may apply to this judgment or decision. The onus remains on any person using material in the judgment or decision to ensure that the intended use of that material does not breach any such order or provision. Further enquiries may be directed to the Registry of the Court or Tribunal in which it was generated.
Decision last updated: 07 April 2022
See below form, call us 7 days till late on 1300-327123 or use one of the instant chat icons in the bottom corners of this page to chat with us now, 7 days till late.
For more information - chat with us live using our instant chat tools (bottom corners), book an appointment or call now on 1300-327123 (till late).
To contact us with any tip-offs, files or information - please use the instant chat tools or form below:
[hubspot portal="4799618" id="7979eaeb-4207-45a9-9392-f066eb15cff2" type="form"]
 Mark Smith : 8 November 2019, 12:47:21 pm AEDT
About Fiona Hall director of Caernarvon Cherry Pty Ltd of Canobolas Rd, Orange NSW 2800.
 Mark Smith : 16 January 2021, 1:54:50 pm AEDT
Employer masterclass: lessons from Biteriot?
 Mark J Smith | MBA, Juris Doctor Founder & Chief Story Teller, CourtList : 4 September 2021, 6:03:55 pm AEST
Explore the latest episode, S1E7 of the Many R's Podcast, where host Mark Smith delves into various topics including insolvency, real estate agents,...
 Mark J Smith | MBA, Juris Doctor Founder & Chief Story Teller, CourtList : 14 January 2021, 1:01:12 pm AEDT
Meet the Biteriot team: Claudio Cianfrano
Mark J Smith | MBA, Juris Doctor Founder & Chief Story Teller, CourtList : 10 January 2021, 11:45:04 am AEDT
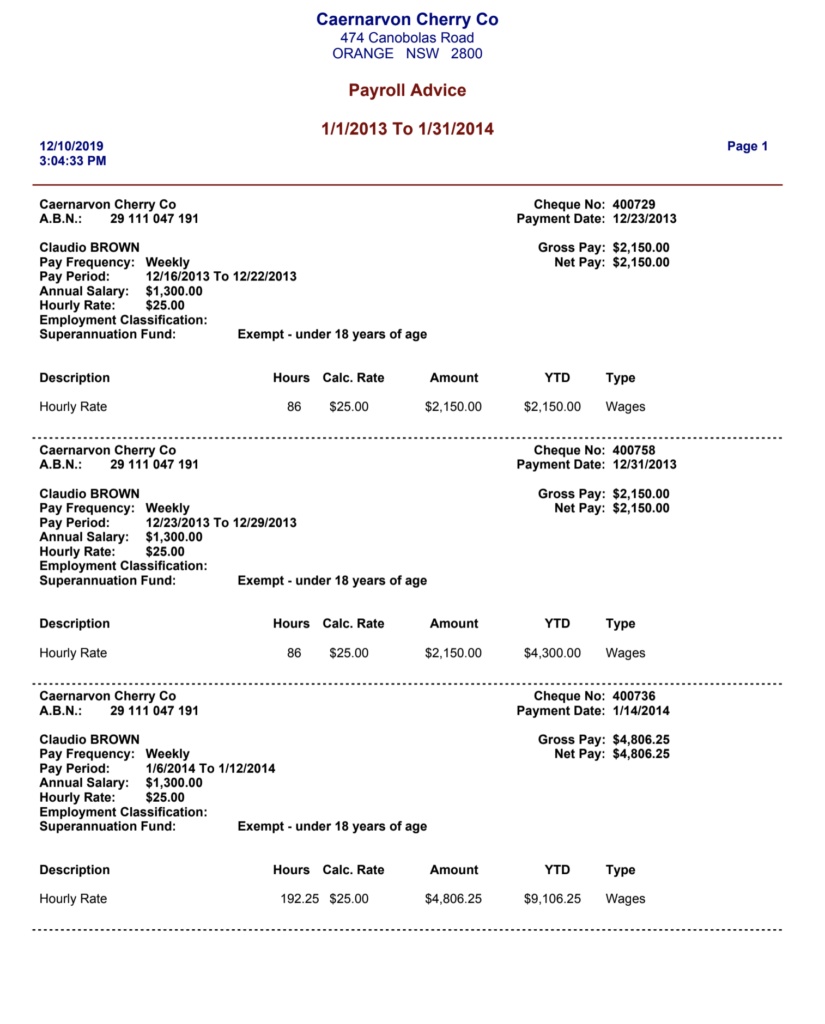
Discover intriguing payroll fun facts in this blog post about Caernarvon Cherry Pty (now Biteriot Operations Pty Ltd) and their alleged employment...
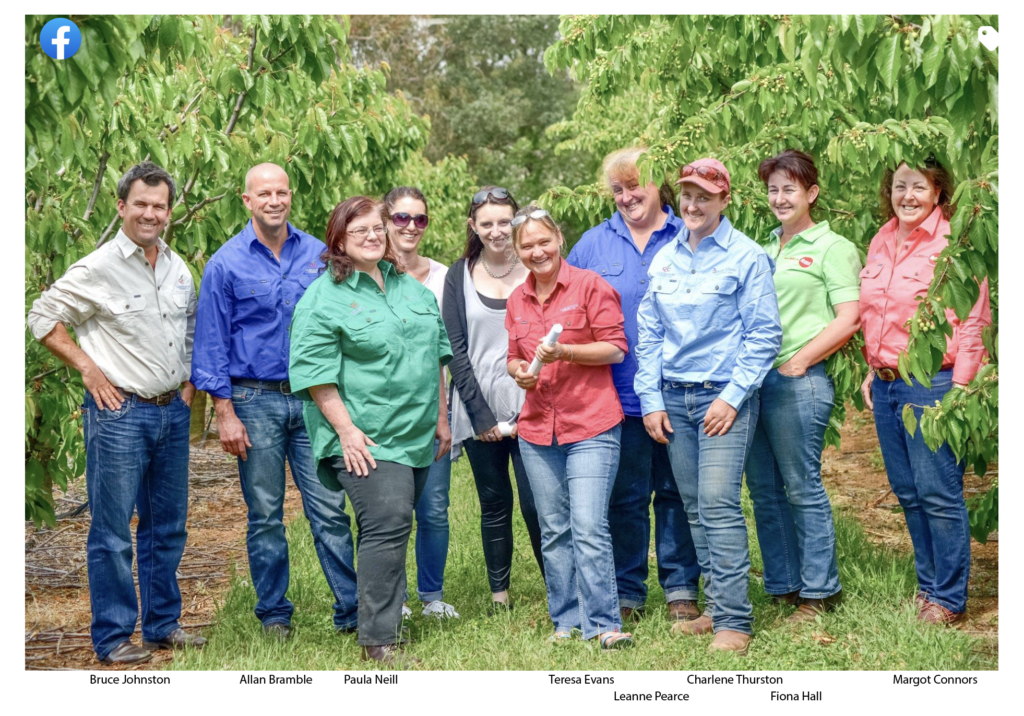 Mark Smith : 12 January 2021, 5:04:00 am AEDT
Caernarvon Cherry: Meet the team & fun facts
 Mark J Smith | MBA, Juris Doctor Founder & Chief Story Teller, CourtList : 8 January 2021, 4:11:38 pm AEDT
Biteriot's export cherry sales to China have plummeted by 75%, revealing flaws in their business model. Challenges include fierce competition from...
 Mark J Smith | MBA, Juris Doctor Founder & Chief Story Teller, CourtList : 4 May 2021, 10:07:36 am AEST
Discover the story of Andrew Gartrell, a former fruit grower turned property developer in the Philippines. Learn about his projects, including...
Mark J Smith | MBA, Juris Doctor Founder & Chief Story Teller, CourtList : 4 October 2020, 12:22:00 pm AEDT
Discover the captivating world of rogues, rascals, rorts, rip-offs, and reviewables in S1E2 of the Many R's Podcast. Mark Smith from DC Partners...